Filipinos in Singapore
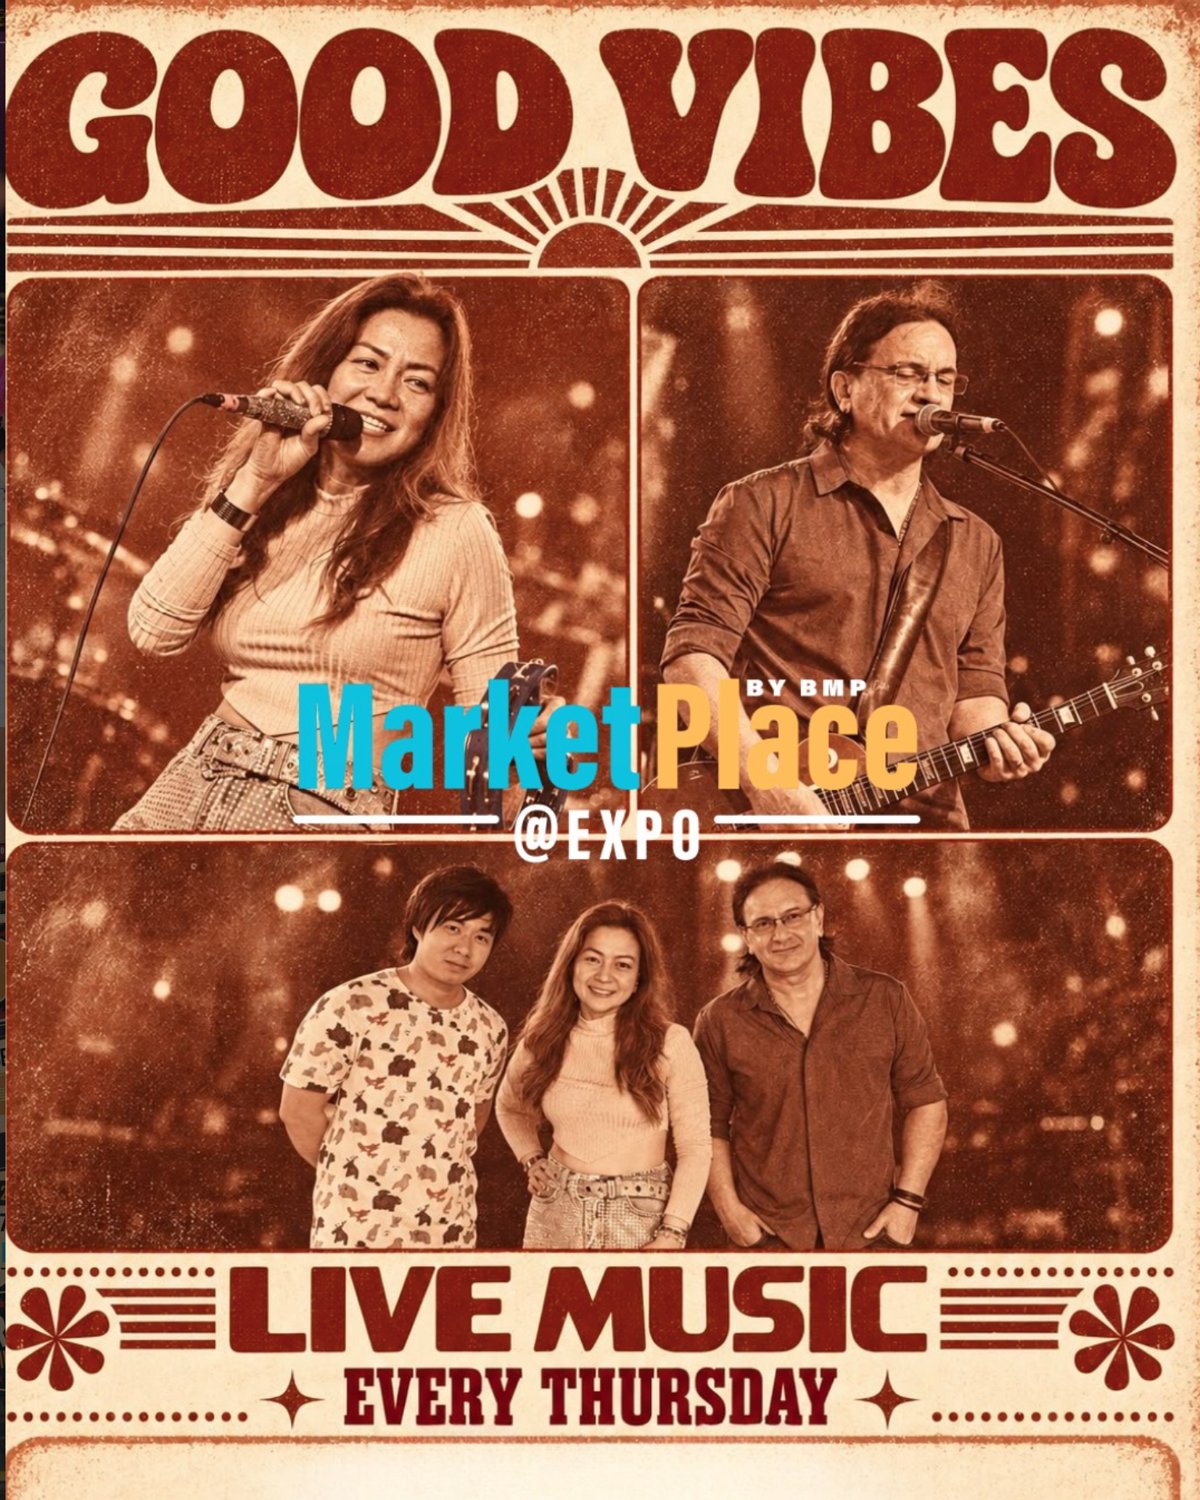
MarketPlace @ Expo: Donna with Good Vibes Band: Live OPM ThursdaysNext upDonna with Good Vibes Band: Live OPM ThursdaysThu 8 & 15 Oct, 7.30pm · MarketPlace @ Expo · Free entryView
Money

Building a PH Retirement Fund from Your Singapore Salary (SSS Voluntary, MP2, PERA — 2026 Guide)

Kahit OFW ka sa Singapore, kaya mong magtayo ng dignified retirement back home using SSS Voluntary, Pag-IBIG MP2, mutual funds, at PERA. Real-numbers guide.

By Audrey Giron··3 min read·Updated 17 May 2026
An elderly Filipino couple watching a Cebu sunset — editorial scene-setter for a retirement planning guide
Share
Add to Google

Advertisement

You can build a PH retirement fund from your Singapore salary even without CPF. This 2026 guide for OFWs in Singapore covers four pillars: SSS Voluntary, Pag-IBIG MP2, mutual funds and PERA.

Pillar 1: SSS Voluntary (for OFWs)

If you worked in PH before moving to SG, you have an SSS number and can keep contributing as a Voluntary Member (OFW).

  • Cap: Monthly Salary Credit (MSC) up to PHP 30,000 as of 2024 rates.
  • Max monthly contribution at PHP 30,000 MSC: PHP 4,200 (14% rate).
  • Why it matters: SSS pension is the only inflation-indexed PH retirement payout. It adds death, disability and funeral benefits, plus maternity for dependents.
  • How to pay from SG: SSS Mobile App, BPI Online, or GCash.
  • Sample plan: PHP 4,200 × 12 × 30 years = ~PHP 1.5M total contributed. Current pension at 65 with full MSC: around PHP 16,000–22,000/month, depending on credited years.

Pillar 2: Pag-IBIG MP2

  • What: Pag-IBIG's optional 5-year savings program.
  • Returns (2024 published rate): 6.92% per annum, tax-free dividends. SG's OCBC 360 base and POSB pay ~0.05%.
  • Cap: unlimited (no upper limit on contribution).
  • Liquidity: locked 5 years; partial withdrawal at maturity or full re-enrol.
  • How to enrol from SG: Pag-IBIG Virtual; contribute via GCash or BPI/BDO.
  • Sample plan: PHP 5,000/month × 5 years = PHP 300,000 in. At 6.92% compounding tax-free = ~PHP 360,000+ at maturity. Roll over.

Pillar 3: Mutual Funds + UITFs in PH

For 10+ year horizons, equity beats fixed income.

  • Categories: Philippine equity index, balanced (60/40), global equity.
  • Vehicles: BPI ALFM, Sun Life Prosperity, Philequity, ATR, COL Financial (for stocks).
  • Returns (long-term avg): ~7–10% per annum for PH equity (rough, varies).
  • Cost: management fees of ~1.5–2% per year eat into returns. Index funds preferred.
  • Cap: unlimited.

Pillar 4: PERA (Personal Equity & Retirement Account)

  • What: A government-backed retirement savings account with a 5% income tax credit on contributions (capped).
  • Cap: PHP 100,000/year for residents; PHP 200,000/year for OFWs.
  • Investment options: mutual funds, UITFs, government bonds, listed shares.
  • Lock-in: withdraw at age 55 with at least 5 years of contribution; tax-free.
  • Where to open: BPI, BDO, Land Bank, RCBC, ATRAM, ATRAM Trust.
  • Sample plan: PHP 200,000/year × 25 years = PHP 5M contributed. At ~7% avg return = ~PHP 13M+ at age 55.

Advertisement

The OFW 50-30-20 retirement plan template

For a Filipino sa SG making SGD 4,500/month:

SSS Voluntary (max)
Monthly
PHP 4,200 (~SGD 100)
Annual
PHP 50,400
25-year impact
PHP 16-22k pension/month at 65
Pag-IBIG MP2
Monthly
PHP 5,000 (~SGD 120)
Annual
PHP 60,000
25-year impact
PHP ~360k every 5-yr roll
Mutual fund / UITF
Monthly
PHP 5,000 (~SGD 120)
Annual
PHP 60,000
25-year impact
PHP ~3M+ at 25 yrs
PERA
Monthly
PHP 16,666 (~SGD 400)
Annual
PHP 200,000
25-year impact
PHP ~13M+ at age 55
TOTAL
Monthly
~SGD 740/month
Annual
PHP 370,400/year
25-year impact
Multi-decade retirement security

That's ~16% of a SGD 4,500 salary going to PH retirement. Doable for most kababayans; swap pillars if cashflow is tight.

Advertisement

Common mistakes

  1. All-in on Pag-IBIG. Solid but capped at 6.92%. Equity does better over 20+ years.
  2. Skipping SSS as "small." It's the only inflation-protected piece.
  3. Buying PH life insurance as "investment." Most VUL products return less than simple index funds. Insurance ≠ investment.
  4. Ignoring PERA. The tax credit alone pays off at OFW caps.

Related reading

Last reviewed 11 May 2026. Rates and contribution caps per SSS, Pag-IBIG, and BIR publications as of late 2025–early 2026; verify current figures before contributing. Not financial advice. Investment returns are not guaranteed; consult a licensed PH financial planner for specific recommendations.
Share

Free tools

See all

Get this in your inbox

One email a week: the news, deadlines and deals that matter for Filipinos in Singapore.

Yes, send me the filipinos.sg email for Filipinos in Singapore. I can unsubscribe from any email. See our privacy policy.

#Money#Retirement#SSS#Pag-IBIG MP2#PERA#Investing#OFW#Filipinos in Singapore